

Squarespace got bigger, richer, and more capable. Somewhere along the way, it also became harder to explain why people loved it in the first place.
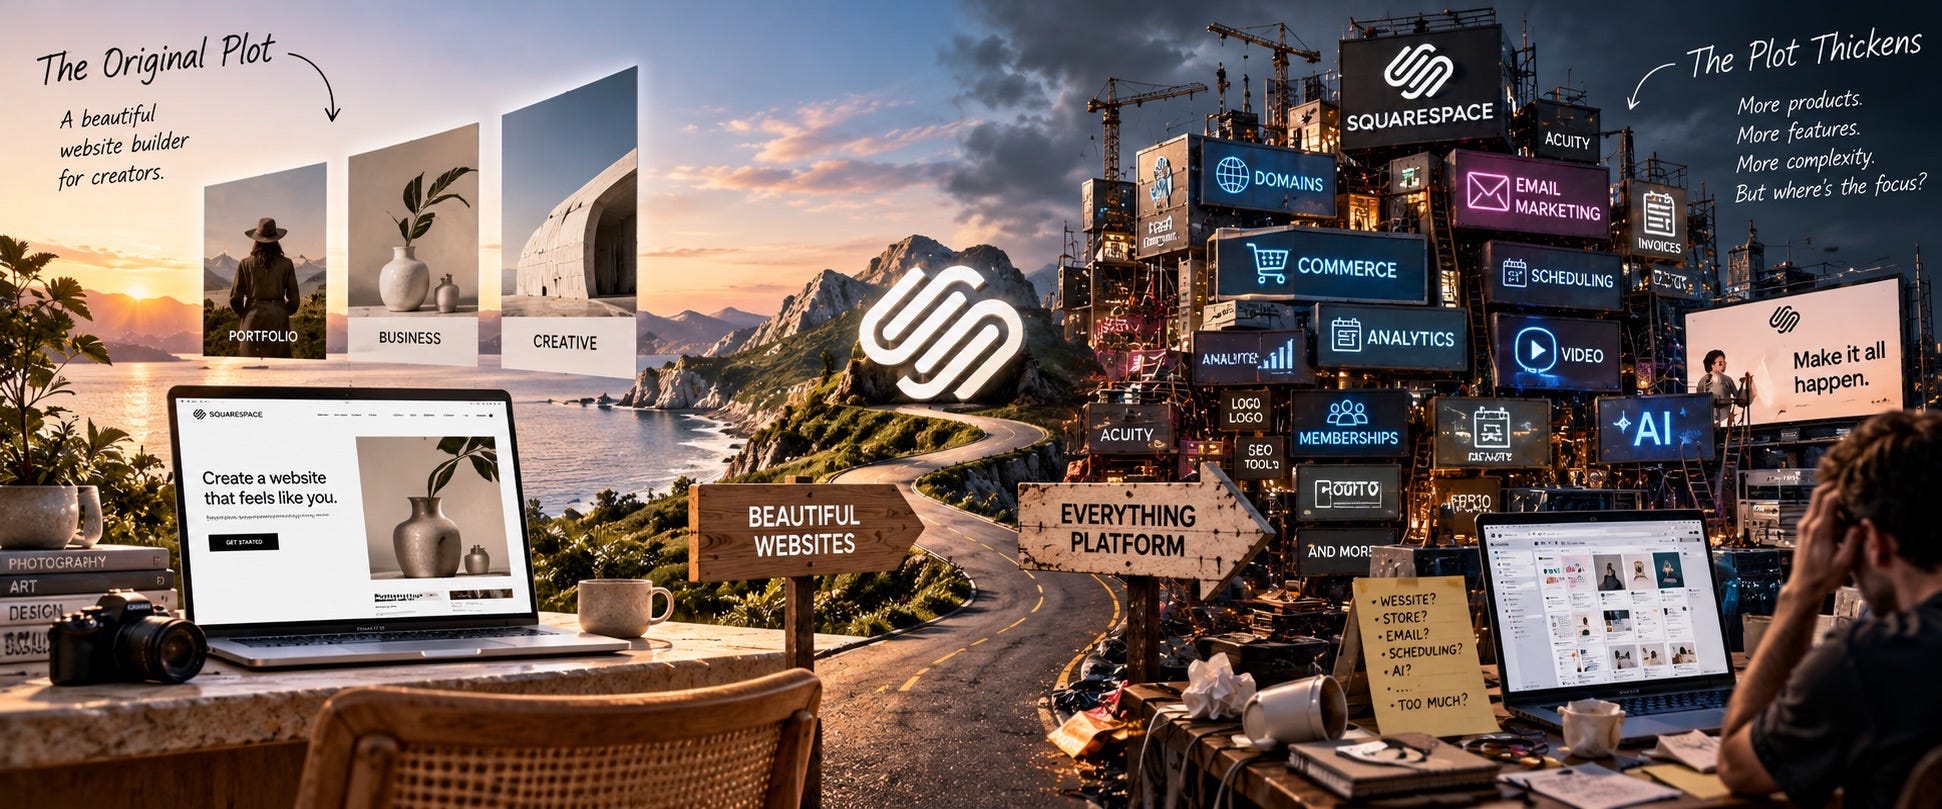
There was a time when recommending Squarespace required approximately seven words:
“Use Squarespace. Your website will look good.”
That was basically the pitch.
You didn’t need to explain hosting infrastructure. You didn’t have to discuss plugins, payment processors, CSS frameworks, database configurations or whether Mercury was in retrograde when WordPress last updated itself. Squarespace took the ugly machinery of publishing on the web and hid it behind beautiful templates and unusually strong design guardrails.
Founder Anthony Casalena described the original problem rather elegantly. When he started building Squarespace in his college dorm room, the existing options required users to cobble together blogging software, analytics, page-building tools and hosting. His response was to build what he called an “elegant solution” that put those pieces together while caring deeply about design. Read Casalena’s early interview about the origins of Squarespace
That clarity turned Squarespace into one of the defining software brands of the 2010s.
Then something strange happened.
Squarespace became a much larger company. Revenue passed $1 billion. Millions more customers arrived. It bought businesses, entered commerce, payments, domains, scheduling, financing and AI. Its cash generation improved dramatically.
And yet, by 2026, a noticeable contingent of longtime customers talks about Squarespace as though someone bought their favourite neighbourhood café, installed self-checkout machines, added a cryptocurrency kiosk and raised the price of coffee.
The tempting conclusion is that Squarespace failed.
It didn’t.
The more interesting conclusion is that Squarespace may have fallen into one of product management’s most dangerous traps:
It confused expanding the value proposition with strengthening the value proposition.
The original Squarespace was opinionated — and that was the feature
Squarespace’s early brilliance wasn’t that it gave users unlimited freedom.
It did almost the opposite.
It constrained users.
Its templates, layouts, typography and design system pushed ordinary people toward reasonably attractive outcomes. You could certainly make an ugly Squarespace website, just as you can burn water if sufficiently talented, but the product worked rather hard to stop you.
Casalena articulated this philosophy beautifully in 2013. He wanted templates to “melt away and be about you,” while Squarespace concentrated on what he called the fundamentals. His conclusion was refreshingly modest:
“We really want to get the fundamentals right.”
Read Casalena’s 2013 discussion of Squarespace’s product philosophy
That philosophy created differentiation.
WordPress offered vastly greater extensibility but frequently demanded plugins, themes, hosting decisions and technical maintenance. Shopify increasingly became the obvious choice for serious e-commerce. Wix offered broad accessibility. Squarespace’s territory was narrower and emotionally clearer:
professional design without professional web-development pain.
That was the product soul.
And importantly, “soul” here isn’t some sentimental Silicon Valley incense ceremony. In product strategy, soul means knowing which trade-offs you deliberately make.
Squarespace sacrificed some flexibility to provide confidence.
That was the bargain.
Then the website builder started becoming a business operating system
Expansion began innocently enough.
E-commerce was an obvious extension. Domains were obvious. Email marketing made sense. If your customers already had websites, helping them transact with visitors was strategically adjacent.
But adjacency has a wonderful property: almost everything eventually becomes adjacent to everything else.
In April 2019, when Squarespace acquired appointment-booking company Acuity Scheduling, Casalena explicitly described the strategic transition:
“We’ve moved beyond helping our customers build great websites.”
The new goal was helping customers “build and run great businesses.” Squarespace’s Acuity acquisition announcement
That single sentence explains much of what followed.
Squarespace stopped defining its competitive arena as website creation.
Its arena became small-business software.
By the time Squarespace filed to go public in 2021, its SEC prospectus described three broad pillars: Presence, Commerce and Marketing. The platform already included websites, domains, e-commerce, social-media tools, marketing and scheduling. Squarespace told investors it could serve customers from their first website through increasingly sophisticated business needs. Read Squarespace’s 2021 S-1 filing
This is perfectly rational SaaS strategy.
A website customer paying you $150 a year is nice.
A business buying its domain, website, email marketing, scheduling, commerce, payments and other services from you is much nicer.
More products increase average revenue per customer. Integrated products create switching costs. Higher switching costs improve retention. Investors enjoy all three things almost as much as software companies enjoy describing price increases as “continued investment in customer value.”
The problem is that the logic of a platform company and the logic of a beloved product are not always identical.
COVID gave Squarespace a glimpse of hypergrowth
Then came 2020.
Businesses suddenly needed to operate online. Restaurants needed digital ordering. Consultants needed booking systems. Retailers needed e-commerce. Creators needed somewhere other than Instagram to make money.
Squarespace revenue jumped from $484.8 million in 2019 to $621.1 million in 2020 — an increase of roughly 28%. By 2021 revenue had reached $784 million.
The pandemic didn’t create Squarespace’s opportunity, but it poured rocket fuel into it.
Private investors noticed.
In March 2021, just before Squarespace went public, the company raised approximately $300 million at a staggering $10 billion valuation. Squarespace’s $10 billion financing announcement
Two months later, reality arrived wearing an NYSE badge.
Squarespace directly listed its shares in May 2021 with a $50 reference price. Shares opened at $48 and later traded around $43.70 on their first day, putting the market capitalization below $6 billion — dramatically below that $10 billion private valuation from only two months earlier.
The market wasn’t saying Squarespace was worthless.
It was saying:
This is a good company. We are less certain it is a hypergrowth company.
That distinction would increasingly define Squarespace’s next chapter.
The Tock adventure: $400 million out, $400 million back
Perhaps no episode better illustrates Squarespace’s platform ambitions than Tock.
In March 2021, Squarespace bought the restaurant reservation, table-management, takeout and events platform for more than $400 million. The logic sounded plausible: restaurants need websites, reservations, payments and marketing, so why not integrate the whole customer journey? Squarespace announces the Tock acquisition
Then things became uncomfortable.
In 2022 Squarespace recorded a $225.2 million goodwill impairment associated with Tock. The company attributed it partly to deteriorating market valuations, but its filing also cited “a change in product strategy” following management departures. Read the Tock impairment disclosure in Squarespace’s 10-K
Then, in 2024, Squarespace sold Tock to American Express.
Sale price?
$400 million.
Squarespace announces the $400 million Tock sale
Calling the acquisition a total failure would be unfair. Tock operated for three years, contributed revenue, grew its customer base and may have taught Squarespace useful lessons about vertical SaaS. And the headline purchase and sale prices don’t capture everything that happened financially in between.
Still, strategically, it’s difficult to miss the symbolism.
Squarespace spent more than $400 million entering restaurant reservation software, impaired $225 million of Tock-related goodwill, and three years later exited the business for $400 million.
That is an awfully elaborate way of discovering that perhaps your website company does not need to own OpenTable.
Fluid Engine changed something more important than the editor
Meanwhile, Squarespace was confronting a genuine product problem.
The web-design market was evolving.
Webflow offered designers much deeper control. Wix improved dramatically. New design platforms were becoming more flexible. Squarespace’s beautifully constrained editor risked feeling limiting.
The company’s answer was Fluid Engine, launched in 2022 as what Squarespace itself called the biggest change to its core editing experience in a decade. The new system gave users far more freedom to move, resize, layer and position elements. Squarespace said its goal was to balance “ease of use with expressibility.” Squarespace’s technical explanation of Fluid Engine
Again: perfectly rational.
Customers wanted greater control.
Competitors offered greater control.
Therefore, give customers greater control.
Except greater control changes the job the product performs.
The old Squarespace implicitly told users:
Don’t worry. We’ll stop you from screwing this up.
Fluid Engine increasingly told them:
Here are more knobs. Good luck.
Reaction was deeply divided. Some designers loved the flexibility and independent mobile editing. Others complained that site-building took significantly longer and that maintaining desktop and mobile layouts separately increased work. One longtime user summarized the problem particularly well:
“The benefits don’t outweigh the extra handling.”
Another wrote that the old “fixed” blocks that “simply work” were why they had fallen in love with Squarespace. These are anecdotes rather than representative customer research, but the pattern is important because the criticism came disproportionately from exactly the professional users who had learned to exploit Squarespace’s old constraints efficiently.
Fluid Engine wasn’t necessarily a bad product decision.
The deeper problem was segmentation.
Squarespace was simultaneously trying to become easier for novices and more powerful for professional designers.
Those goals can coexist, but only with exceptional product architecture.
Otherwise you end up building Photoshop for someone who originally wanted Instagram filters.
Meanwhile, the competitive battlefield moved underneath Squarespace
Squarespace didn’t stop growing.
But competitors moved faster.
According to W3Techs’ historical CMS usage estimates, Squarespace’s share among sites using a known CMS increased from roughly 2.3% in early 2021 to 3.5% in August 2026.
That’s growth.
But during roughly the same period, Wix climbed from 2.4% to 6.1%, while Shopify moved from 5.2% to 7.7%. Different platforms serve overlapping rather than identical markets, and W3Techs is measuring observed website technology rather than company revenue or subscriptions, so this isn’t a definitive competitive scoreboard. But directionally it illustrates the problem: Squarespace expanded while rivals expanded faster. Explore W3Techs’ historical CMS market-share data
Worse, Squarespace’s original differentiator became easier to copy.
Good templates are no longer rare.
Design systems improved.
Webflow pushed upward into professional development.
Framer attacked the designer market.
Shopify became extraordinarily difficult to challenge in serious commerce.
Wix broadened its website-building platform.
And generative AI introduced an entirely new threat: if an AI system can generate a decent website from a paragraph, “build a professional website without coding” becomes less of a moat and more of a checkbox.
Squarespace therefore faced exactly the strategic dilemma that kills many successful products:
The feature that made you famous eventually becomes table stakes.
The answer cannot simply be “add everything.”
But adding everything is extremely tempting.
Google Domains: strategically brilliant — and another identity shift
Squarespace made one particularly clever expansion in 2023.
When Google decided to exit its domain-registration business, Squarespace acquired the Google Domains assets for $180.7 million. The migration involved approximately 10 million domains across millions of customers. Squarespace’s Google Domains acquisition announcement
This deal makes far more strategic sense than Tock.
Domains sit directly upstream of websites.
Someone buying myamazingbusiness.com is an extremely attractive prospect for hosting, websites, commerce, email and marketing. Google was essentially handing Squarespace millions of potential customers standing at the entrance of Squarespace’s funnel.
By 2024, Squarespace described itself as one of the world’s leading domain registrars.
Smart move.
But notice the evolution of the company:
Website builder.
Then commerce platform.
Then marketing suite.
Then scheduler.
Then restaurant reservation platform.
Then domain registrar.
The centre of gravity was moving.
Financially, Squarespace was doing much better than the “downhill” narrative suggests
This is where the simplistic version of the story falls apart.
Squarespace was not deteriorating financially.
Quite the opposite.
Revenue went from $784 million in 2021 to $867 million in 2022 and $1.012 billion in 2023. In 2023, unique subscriptions increased 10% to 4.6 million. Unlevered free cash flow reached $241 million, representing approximately 24% of revenue. Squarespace’s 2023 financial results
By the second quarter of 2024, revenue was growing 20% year over year, unique subscriptions had exceeded 5.2 million and annual run-rate revenue had reached nearly $1.18 billion.
That is not what corporate death looks like.
It is what a maturing subscription business looks like.
And this is precisely why the Squarespace story is useful for product leaders.
Companies don’t need to be financially failing to lose product coherence.
Sometimes the spreadsheet improves while the product narrative gets worse.
The telltale metric: more growth started coming from price
Look more closely at the 2023 numbers and another pattern emerges.
Squarespace’s Presence revenue grew by approximately $107 million that year.
Of that increase, $34.3 million — 32% of the incremental Presence growth — came from price increases across website subscription plans. Across Squarespace’s subscription offerings, management said pricing generated roughly $39 million, or 27% of total revenue growth, during 2023.
Again, raising prices isn’t evidence of villainy.
If a product delivers greater value, charging more is healthy. SaaS companies that never increase prices eventually discover inflation the way Wile E. Coyote discovers gravity: suddenly and several seconds too late.
But pricing becomes strategically interesting when customers perceive the product’s additional value differently from the company.
Squarespace sees:
more commerce
more AI
more payments
more marketing
more scheduling
more financial tools
more business functionality.
The photographer with a six-page portfolio may see:
the same six-page portfolio.
That difference between platform value and customer-perceived value is where resentment grows.
Then Squarespace went private
In October 2024, investment firm Permira completed its acquisition of Squarespace for approximately $7.2 billion. Casalena rolled over most of his equity, remained a major shareholder and continued as CEO. Permira’s announcement completing the Squarespace acquisition
The valuation comparison is fascinating.
March 2021 private valuation: $10 billion.
October 2024 take-private transaction value: $7.2 billion.
And yet between those dates, Squarespace revenue had grown dramatically.
This says more about 2021’s exuberant technology valuations than it does about Squarespace’s operational performance. In fact, proxy adviser ISS initially objected to Permira’s lower offer because it believed Squarespace’s improving performance suggested shareholders deserved more. Permira ultimately raised the offer from $44 to $46.50 per share.
Private equity also does not automatically mean “company ruined.”
Squarespace is almost a textbook attractive PE asset: recurring subscription revenue, strong brand recognition, healthy retention, meaningful pricing power and substantial free cash flow.
But private ownership changes the incentives.
Growth, margin expansion and monetization matter enormously.
Which brings us to 2026.
From websites to AI, lending and bank-like accounts
If going private was supposed to return Squarespace to being a simple website builder, apparently nobody told the product roadmap.
By 2025 and 2026, Squarespace had expanded even further.
It introduced Squarespace Capital, providing eligible merchants access to financing. It expanded native payments. It developed Blueprint AI, AI-generated content, SEO/AIO tools and an AI business assistant called Beacon. It launched tools specifically for professional designers and agencies. Squarespace Capital announcement Squarespace Refresh 2025
Then, in March 2026, came Squarespace Balance: a business financial account integrated with Squarespace Payments, complete with a Visa card and rewards on balances.
Squarespace’s own executive described it this way:
“Squarespace Balance rounds out our suite of financial tools.”
Read the Squarespace Balance announcement
Compare that with Casalena in 2013:
“We really want to get the fundamentals right.”
There is nothing inherently wrong with business banking, payments or lending.
But when the company that became famous for making beautiful websites is discussing its “suite of financial tools,” you can reasonably ask whether the strategic centre of gravity has moved.
The product isn’t merely expanding anymore.
The definition of Squarespace itself is expanding.
And then came the 2026 pricing backlash
In July 2026, some longtime Squarespace customers received startling renewal notices.
Screenshots and reports posted online included increases that appeared to approach 50%, 70% and, in one widely discussed case, roughly 82% — from $192 to $348 annually. Unsurprisingly, the reaction was roughly as calm as discovering your landlord has replaced your rent with surge pricing.
But there’s an important correction.
Squarespace subsequently stated that some notices contained an error. In a post from its official Reddit community, the company said a small number of customers had been shown increases as high as roughly 70%, but that the correct increase was capped at 20% and nobody had been charged the erroneous amount.
That’s considerably less scandalous.
It’s also still a meaningful increase.
Squarespace’s own support documentation confirms that it periodically adjusts legacy-plan pricing as the platform evolves. The old Personal, Business and Commerce plans have now been replaced by Basic, Core, Plus and Advanced plans. Squarespace’s current explanation of legacy plan pricing
The anger reveals something deeper than price sensitivity.
A recurring theme in customer discussions is not simply:
“Twenty percent is too expensive.”
It is:
“I don’t use all this stuff.”
That is a dangerous sentence for a platform company.
Because once customers mentally separate the thing they value from the things they are paying for, bundling starts to feel like bloat.
Is customer satisfaction actually collapsing?
The evidence is messier than Reddit makes it look.
Squarespace’s Trustpilot profile, for example, sits at roughly 3.5 out of 5 across more than 5,000 reviews as of August 2026. The distribution is strikingly polarized: about 38% five-star and 42% one-star. Recent reviews include both praise for responsive support and complaints about limited support availability and difficult technical escalations. See current Squarespace customer reviews on Trustpilot
Squarespace officially offers 24/7 email support and weekday live chat, so claims that it provides “no support” are plainly exaggerated. Squarespace’s official customer-support options
This matters because product post-mortems become useless when we selectively collect angry Reddit threads and call them data.
Squarespace still has millions of customers.
Its observed web presence continues growing.
Many customers like Fluid Engine.
Many businesses benefit enormously from integrated commerce and payments.
The company is clearly not universally hated.
So what exactly went wrong?
Squarespace didn’t lose product-market fit. It diluted it.
That’s the distinction.
Classic product-market fit asks:
Does this product solve an important problem for enough customers?
Squarespace clearly still does.
But mature platforms face another question:
Can customers still understand why this product is uniquely for them?
That’s where Squarespace’s position looks weaker.
Its original differentiation was unusually sharp:
beautiful, professional websites without technical complexity.
Its modern proposition is closer to:
an integrated AI-enabled entrepreneurial platform spanning online presence, commerce, domains, marketing, scheduling, payments, financing, financial accounts and business management.
The second opportunity is much larger.
It is also much less distinctive.
Shopify can credibly tell merchants: We are commerce.
Webflow can tell professional designers: We give you control.
WordPress can say: You can build almost anything.
Framer can position around modern interactive design.
Squarespace increasingly says:
We do all of that, sort of.
That is strategically dangerous territory.
The real mistake wasn’t adding features
The lazy lesson from Squarespace would be:
“Stay focused. Don’t build platforms.”
That’s wrong.
Platforms can be extraordinarily powerful. Shopify is vastly more valuable because it expanded beyond a simple storefront builder. Microsoft would be a somewhat smaller company if it had stopped after Word.
The real lesson is subtler.
Expansion must reinforce the core job rather than obscure it.
A domain reinforces Squarespace’s core job.
Better typography reinforces it.
AI that intelligently creates a beautiful starting layout reinforces it.
Payments can reinforce it for commercial websites.
Scheduling makes sense for service businesses.
But each additional layer increases cognitive and organizational complexity. Eventually, a company has to decide whether every customer should experience that complexity.
Squarespace appears to have treated platform breadth as almost universally desirable.
That creates what I would call the platform tax.
Customers pay the platform tax three ways: financially through higher pricing, cognitively through more options and strategically through a product increasingly optimized for users who aren’t them.
The six-page photographer’s portfolio now shares a product strategy with an online retailer, restaurant, agency, consultant, course creator, subscription business and merchant looking for financing.
That is impressive.
It is also a lot to ask of one product.
The lesson for product leaders: protect your reason for being
The saddest product failures aren’t necessarily products that stop working.
They’re products that still work perfectly well but cease to feel special.
Squarespace hasn’t become bad software.
In many respects, the 2026 Squarespace platform is objectively more capable than the Squarespace of 2016.
It can do dramatically more.
That’s precisely the problem.
Product teams naturally measure progress by accumulation:
more features
more use cases
more revenue streams
more integrations
more addressable market
more AI, because apparently every button now needs a language model hiding behind it.
But customers don’t experience roadmaps.
They experience products.
And customers frequently prefer something that does one job exceptionally well over something capable of doing seventeen jobs while continuously reminding them of the other sixteen.
Squarespace built its reputation by making decisions on behalf of customers.
It decided what good typography looked like.
It decided how layouts should behave.
It imposed design constraints.
It hid complexity.
It gave ordinary people confidence.
Then, as Squarespace matured, much of its strategy moved in the opposite direction: more flexibility, more business functions, more products, more monetization, more customer segments and more responsibility placed on the platform to serve all of them.
The irony is almost perfect.
Squarespace won by simplifying the web. Then it spent years rebuilding the complexity it had originally removed — only this time inside Squarespace.
The company may yet pull it off
There is a bullish interpretation.
Domains create a huge acquisition funnel.
AI may restore simplicity by hiding platform complexity behind conversational interfaces.
Payments, Capital and Balance could turn Squarespace into a genuinely compelling operating system for small businesses.
Its 2025 investment in professional designers could improve its position against Webflow and Framer. Its commerce improvements could increase merchant retention. And private ownership gives management more freedom to invest without explaining every quarter to Wall Street.
Squarespace’s current market footprint certainly doesn’t resemble a dying platform. W3Techs estimates it powers around 2.5% of all websites and 3.5% of websites whose CMS is known as of August 2026.
Perhaps Squarespace hasn’t lost its soul.
Perhaps it is trying to find a bigger one.
But that transition carries a serious risk.
A company can expand its total addressable market so aggressively that it weakens the reason anyone chose it in the first place.
And that is the strategic lesson Squarespace offers.
Not:
Never expand.
Not:
Never raise prices.
Not even:
Never let private equity buy you.
The lesson is:
Never allow your platform strategy to become more legible to your investors than your product strategy is to your customers.
Squarespace’s greatest achievement was never that it let people create websites.
The internet already allowed that.
Its achievement was removing hundreds of decisions ordinary people shouldn’t have needed to make.
That feeling — don’t worry, we’ve thought about this for you — was the real product.
Everything Squarespace adds should strengthen that feeling.
Because once customers start thinking, Why am I paying for all of this?, you’ve already moved from selling value to explaining complexity.
And explaining complexity is precisely the business Squarespace was invented to eliminate.